Doing business in Vietnam
Amid global volatility, Vietnam has demonstrated real progress in restructuring its economy, reinforcing confidence in its long-term growth trajectory. The country continues to position itself as a strategic bridge between East and West. On one hand, it is a direct beneficiary of the China Plus One policy, with the government also focusing on improving infrastructure and tax incentives to attract increased levels of foreign investment. On the other, US investors continue to be an important source of capital. Additionally, South Korean, Japanese and Singaporean firms have established a significant presence in Vietnam in recent years.
However, there are still obstacles for foreign companies to overcome, including a lack of transparency and weak enforcement of intellectual property rights. Companies should first familiarise themselves with the local business landscape to ensure confident market entry.
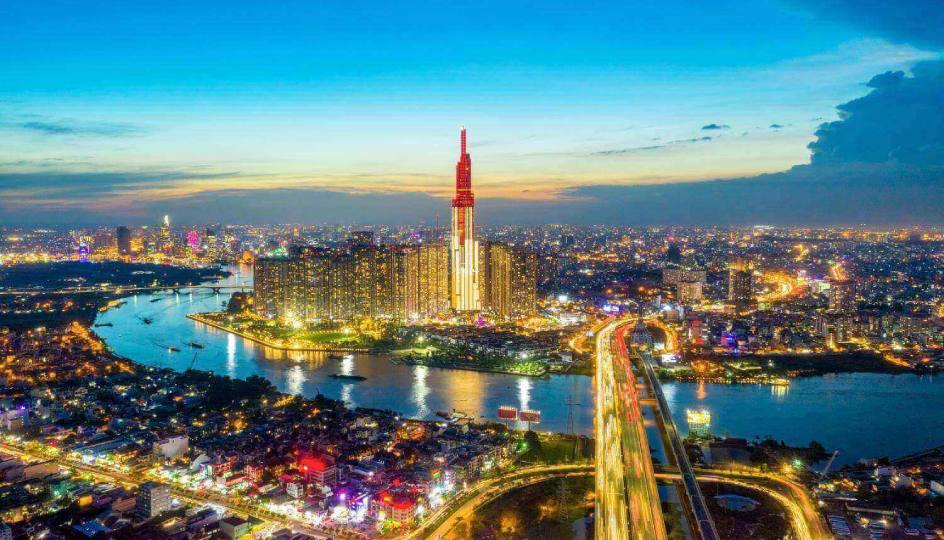
Vietnam, officially the Socialist Republic of Vietnam (SRV), is a country at the eastern edge of Southeast Asia, spanning an area of around 331,000 square kilometers. Vietnam shares land borders with China to the north and Laos and Cambodia to the west. It also has maritime borders with Thailand, the Philippines, Indonesia and Malaysia.
It is one of the fastest-growing economies in the region, offering businesses political stability, an improving investment climate, competitive production costs, an abundant workforce and broad access to international markets. Vietnam benefits from the China Plus One policy, with companies looking to diversify supply chains and seeking more cost-effective manufacturing hubs outside of Mainland China. The country’s capital is Hanoi and its largest city is Ho Chi Minh City, which is the nation’s financial centre.
Vietnam is actively involved in a number of international membership organisations and free trade agreements (FTAs). These include, among others, the Association of Southeast Asian Nations (ASEAN), the ASEAN Free Trade Area (AFTA), Asia-Pacific Economic Cooperation (APEC), the World Trade Organization (WTO) and the EU-Vietnam Free Trade Agreement (EVFTA).
| Fast facts: |
|
TMF Group’s Global Business Complexity Index (GBCI) shows that Vietnam has seen an increase in business complexity over the past year, rising 13 places to 41st in the GBCI 2026 rankings. Fast-changing legal and administrative requirements across service lines in the country are driving this complexity, especially as digitalisation and provincial mergers are reshaping how businesses set up and operate.
Advantages of doing business in Vietnam
Vietnam is developing into a compelling commercial success story, with the economy expected to achieve double-digit growth over the next few years. Economic reforms and beneficial global trends have combined to propel the country from being one of the poorest in the world to a middle-income economy within a single generation.
This economic growth is driven by an expanding domestic market and a young, educated and hard-working population that has emerged as one of the fastest-growing middle classes in Asia. As well as access to a skilled and affordable workforce, companies doing business in Vietnam benefit from its strengthening position as a major manufacturing hub, particularly as a China Plus One destination.
Other advantages include favourable trade conditions and a spike in high-tech investments, particularly in the electronics sector. Vietnam is also home to hundreds of fintech start-ups, which offer a wide range of services, including digital payments, alternative finance and wealth management. The country’s key hubs include Binh Duong and Dong Nai, which are near Ho Chi Minh City, as well as Bac Ninh, Bac Giang and Hai Phong.
Investing in Vietnam
The government has made a concerted effort in recent years to improve the country’s infrastructure, and to implement institutional reforms and new strategic initiatives to encourage greater foreign interest and attract increasing levels of foreign direct investment (FDI) into Vietnam. It has accelerated upgrades to transportation and logistics infrastructure, including highways, ports and digital connectivity to support industrial expansion and global supply chain integration.
In 2025, there were a number of significant breakthroughs in terms of infrastructure development. A series of new expressways such as Nghi Son-Dien Chau, Nha Trang-Cam Lam, Vinh Hao-Phan Thiet, Ring Road 3 in Ho Chi Minh City and Ring Road 4 in Hanoi were opened to traffic. This brought the country’s total expressway length to over 3,000 kilometres – a symbolic milestone reflecting the government’s effectiveness.
The government has also pushed forward administrative reforms aimed at reducing red tape, targeting cuts of at least 30% in terms of business conditions. One major legislative milestone is the Revised Law on Investment (adopted December 2025, effective 2026), which significantly simplifies market entry. Notably, foreign investors can now establish a company before obtaining project approval, while many licensing requirements have been reduced or shifted to a post-audit regime. This helps to significantly shorten time-to-market and improve regulatory predictability.
Another major new development is the establishment of Vietnam’s International Financial Centre (IFC), approved in 2025 with hubs in Ho Chi Minh City and Da Nang. The IFC is designed as a strategic platform to attract global capital and financial institutions, offering simplified administrative procedures, more liberal foreign exchange and financial regulations, enhanced dispute resolution mechanisms (including arbitration centres) and long-term visas with favourable immigration policies for foreign experts.
Vietnam continues to benefit from an extensive network of FTAs, including the EVFTA, the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) and the Regional Comprehensive Economic Partnership (RCEP). These help to improve market access and reduce tariffs.
Additionally, in March 2025, Vietnam and Singapore upgraded their relationship to a Comprehensive Strategic Partnership. Singapore is currently the second largest investment partner in Vietnam with total accumulated investment capital exceeding US$80bn. The Vietnam-Singapore Industrial Park (VSIP) model is also evolving into VSIP 2.0, focusing on smart, green and innovation-driven industrial ecosystems, further enhancing Vietnam’s attractiveness to global manufacturers.
The financial and tax environment in Vietnam
Vietnam introduced several major tax law changes in 2025.
Significant investment has also been made in order to digitalise processes across regulatory reporting requirements and accounting and tax systems. All industries in Vietnam can now use e-invoicing, which aligns with global developments, and all tax reports can be filed online via the website of local tax authorities. This has helped businesses to save time and reduce costs and has also helped to ensure the process of setting up operations in the country is as smooth as possible.
The standard corporate income tax rate in Vietnam is 20% and is imposed on a company’s profits, including the profits of any affiliates and branches. The tax rates for business activities in the oil, gas and natural resources sector range between 32% and 50%, in accordance with each project and each business.
Vietnam offers attractive tax incentives to encourage investment, particularly in high-tech and priority sectors. For example, newly established projects in incentivised sectors or locations may benefit from a reduced corporate income tax rate of 10% for up to 15 years. However, the global minimum tax (15%) for multinational enterprises has been in effect since 2025, which may limit the impact of certain tax incentives.
The Vietnamese government also offers location-based incentives for certain regions to attract capital and boost development in these areas. Income in newly invested projects in these regions is subject to 15 years of corporate income tax at a reduced rate of 10%.
The standard rate of VAT in Vietnam is 10%, with a reduced rate of 8% applicable to certain goods and services. There are plans to maintain the 8% rate and expand its applicability to more businesses until the end of 2026. No withholding or remittance tax is imposed on dividends paid to foreign corporate shareholders, or dividends for resident and non-resident companies. However, there is a 5% withholding tax imposed on dividend payments to individuals, except those who are the owners of one-member limited liability companies.
Vietnam has established comprehensive double tax agreements (DTAs) with more than 80 countries, with the aim of fostering increased international trade and investment while also preventing the double taxation of income. These agreements are particularly important for foreign companies engaged in cross-border business or investment activities.
All domestic companies, both listed and unlisted, are required to use the Vietnamese Accounting Standards (VAS) developed by the Vietnamese Ministry of Finance. Generally, the VAS are based on International Accounting Standards (IAS), though some modifications have been made to reflect local accounting regulations.
Hiring and managing employees in Vietnam
Vietnam's Labour Code is the primary legislation governing labour laws in the country. It outlines labour standards, the rights and obligations of both employees and employers and the role of the government in regulating labour. It covers a broad range of provisions, encompassing employment contracts, working hours, wages, overtime, social insurance and termination of employment.
Employers are required to contribute to Vietnam’s social security scheme – which includes social insurance, health insurance and unemployment insurance – for all full-time employees.
Employers hiring foreign workers for specific roles must first advertise for Vietnamese candidates. This notice must be posted on the online portal of the local employment service centre at least five days before submitting a request to employ foreign labour.
All organisations can hire foreign workers if Vietnamese workers are unable to meet the specific requirements of a role.
| Vietnam’s work visa process at a glance: |
|
When it comes to setting up payroll, employee salaries are typically paid monthly, depending on the terms set forth in the employment contract.
Salaries must not be lower than the regional minimum base.
In Vietnam, these regional minimum base salaries are set differently for four regions. As of 2026, the highest is in Region 1 (₫5,310,000 per month), which includes major cities like Hanoi and Ho Chi Minh City, with the lowest in Region 4 (₫3,700,000 per month).
Starting a business in Vietnam
There are a number of different types of business structures used by foreign entities setting up operations in Vietnam.
The most common include limited liability companies (LLCs), where members have liability limited to the extent of their contributed capital, and joint stock companies (JSCs), which are the only type of company that can issue shares and can be listed on the Vietnam Stock Exchange (VNX).
The Vietnam Law of Commerce states that foreign companies may establish a representative office in Vietnam if they have been doing business abroad for one year. A representative office is not an independent entity and is ineligible to conduct direct commercial activities in the country. It is only permitted to act as a liaison office, conduct market research and promote its head office’s business and investment opportunities.
It is crucial businesses choose the correct structure for their circumstances and planned activities when setting up operations in Vietnam. It is advisable to thoroughly research the different options and working with a local expert can help a company to make a more informed choice.
FAQs
1. Can foreign businesses set up a company in Vietnam?
Yes. The Vietnamese government is making a concerted effort to drive foreign interest and attract further investment into the country.
The first step is to select the most appropriate business structure, and then it can take more than 18 days to set up a company in Vietnam, including all the procedures, registrations and obtaining licences. However, as a result of the Revised Law on Investment, foreign investors can now establish a company before obtaining project approval, while many licensing requirements have been reduced or shifted to a post-audit regime.
Furthermore, the Vietnamese government is considering abolishing regulations regarding Investment Registration Certificates in the latest draft of Vietnam’s Investment Law. Consequently, the process of establishing foreign businesses in Vietnam will likely soon become more streamlined.
2. What are the main challenges of doing business in Vietnam?
Despite the many advantages associated with doing business in Vietnam, there are a number of significant challenges facing foreign companies expanding into the market.
Many of the bureaucratic processes remain complex and there is often a lack of transparency. Vietnam’s regulatory regimes and commercial laws, as well as the overlapping mandates of some government ministries, can sometimes result in inconsistent government policies. Another issue is the weak enforcement of intellectual property rights.
The merging of many administrative units and restructuring of government authorities that took place across 2025 may also affect administrative processes and procedures in the short term.
Companies seeking to expand into the country with confidence should first familiarise themselves with our article outlining the main challenges of doing business in Vietnam.
3. What is the business culture like in Vietnam?
Vietnamese business culture centres around the social connections made between business partners, which is perhaps a lingering effect of Confucianism’s impact on the local people.
Dealmakers must be prepared to share personal information about their family and hobbies as it can improve relationships with local suppliers and ultimately shape business deals. Most connections are made through referrals and recommendations and the price offered can often be dictated by the method of introduction.
Seniority is also important, especially when dealing with the government or state-owned organisations. Collective decision-making plays a big role in Vietnamese business culture. Most decisions are made by committee with no individual having absolute power. This makes fostering a group connection, rather than just individual connections, a particularly important consideration when doing business in Vietnam.
Request our in-depth guide to learn more about doing business in Vietnam.
Request now Request now