Doing business in Estonia
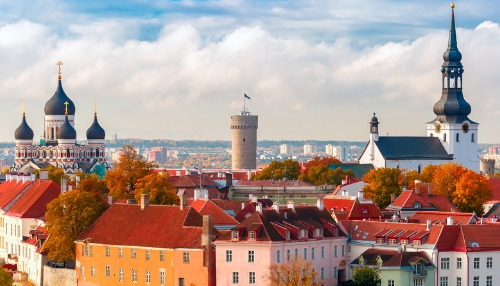
Estonia offers international businesses access to the European Union market, established company structures and an electronic route to incorporation.
Companies expanding into the region must plan for local tax, employment, governance and reporting requirements.
Estonia, officially the Republic of Estonia, is located in the Baltic region of northern Europe. It borders the Gulf of Finland, the Baltic Sea, Latvia, Lake Peipus and Russia. Its economy grew by an estimated 0.6% in 2025, with real GDP growth projected at 1.6% in 2026 and 1.7% for 2027.
Estonia is a member of the European Union and several international organisations, including the World Bank, United Nations, World Trade Organization (WTO), International Monetary Fund (IMF), North Atlantic Treaty Organization (NATO), Organisation for Economic Co-operation and Development (OECD) and Organisation for Security and Co-operation in Europe. This places Estonian businesses within established European customs and international cooperation frameworks.
International investors can use private or public limited companies, partnerships, a commercial association or a branch. Estonia also offers electronic incorporation for qualifying private limited companies. The appropriate route depends on ownership, capital, liability, governance and the expected duration of the local operation.
| Fast facts: |
|
Advantages of doing business in Estonia
Estonia combines its European Union membership with access to the European Union Customs Union. Goods moving between Estonia and other European Union countries are free from customs duties. Imports from outside the European Union follow the common external tariff, while European Union free trade agreements also apply.
Qualifying investors can choose from several legal forms and, for a private limited company, may use electronic registration where the participants can digitally sign the incorporation documents. This can simplify the initial filing route, although the planned ownership and capital contribution must meet the electronic process requirements.
Estonia has three operational free zones in Paldiski, Muuga and Sillamäe. Goods brought into a free zone for later re-exportation are not subject to value added tax, excise or customs duties. Estonia’s treatment of reinvested profits also applies within the free zones. Businesses should assess whether their supply chain and planned activity fit the customs treatment available.
Choosing the right business structure in Estonia
Private limited companies, or Osaühing (OÜ), and public limited companies, or Aktsiaselts (AS), are the structures most commonly used by foreign investors in Estonia. An OÜ divides its capital into shares and requires a minimum share capital of €0.01 per shareholder. The company is liable with its own assets, while each shareholder is liable up to their contribution.
An AS may be established by one or more natural or legal persons. Its minimum share capital is €25,000. Shares must be registered in the Estonian Central Register of Securities. Shareholders are not personally liable for the company’s obligations, while the company remains liable with its assets.
A general partnership requires at least two partners who are personally liable for its obligations. A limited partnership also needs at least two participants, with at least one general partner liable with all assets and at least one limited partner liable up to their contribution. A commercial association supports members’ shared economic interests and may set different liability arrangements in its articles.
A foreign company can establish a branch to offer goods or services in Estonia. The branch is not a separate legal person, so the parent company is liable for its obligations. The parent appoints one or more directors. If at least half of the directors do not reside in Estonia, the European Economic Area or Switzerland, the foreign company must appoint an Estonian contact person.
Starting a business in Estonia
An OÜ may be registered electronically through Estonia’s e-commercial register or through a notary. Electronic registration is available where everyone involved in the establishment can digitally sign the application and incorporation documents.
The main steps for establishing a private limited company through the e-commercial register are:
- Select a business name and check its availability using the e-business register tool
- Register the company online and pay the state fee and share capital, or choose to defer the share capital payment where available
- Open a bank account
- Register employees in the employment register
- Register for taxes and value added tax where required
Online company registration takes one day and carries a €265 state fee, plus share capital. Opening a bank account can take anywhere between one hour and one week and may cost anywhere between €0 and €200 depending on the bank. Banking can therefore be the most variable step in the timetable.
Where the contribution exceeds €50,000, an electronic financial contribution must be made through the e-commercial register during the application. For smaller contributions, board confirmation is sufficient. Value added tax registration is not obligatory where annual taxable turnover is below €40,000, although specific non-resident transactions can require registration without a threshold.
Corporate governance in Estonia
An OÜ must have a management board. A supervisory board is optional unless the articles of association require one. Board members must be natural persons with full active legal capacity, but there is no nationality or European Union residency requirement. Shareholders appoint and remove management board members.
An AS requires both a management board and a supervisory board. The supervisory board must have at least three members and a person cannot sit on both boards. Where more than half of the relevant board members do not reside in Estonia, the company must provide the Commercial Register with an Estonian contact address for documents.
Public and private limited companies must hold an annual general meeting once per year. The meeting must take place within six months after the financial year-end and include approval of the annual report. The management board calls the meeting and notice must be sent at least three weeks in advance. Companies should build the notice period, approval and reporting deadline into a single governance calendar.
Companies must file annual financial statements within six months after the end of the fiscal year. Statements may follow Estonian Generally Accepted Accounting Principles or International Financial Reporting Standards, depending on the company’s size and international operations.
All public limited companies are subject to audits, while private limited companies become subject to a statutory audit or review when the relevant revenue, asset or employee thresholds are exceeded.
An audit is generally required when at least two of the following thresholds are exceeded:
- Revenue: €5 million
- Balance sheet total: €2.5 million
- Average number of employees: 50
A further audit is required if any one of the following higher thresholds is exceeded:
- Revenue: €15 million
- Balance sheet total: €7.5 million
- Average number of employees: 180
The tax environment in Estonia
Estonia taxes distributed profits rather than retained profits. The general corporate income tax rate increased to 24% from 1 January 2026. Resident companies pay tax on distributed profits from worldwide income, while permanent establishments of non-residents pay tax on distributed profits from Estonian-source income.
Estonia generally does not apply withholding tax to dividends or interest paid to non-residents. Royalties paid to non-residents are generally subject to 10% withholding tax under domestic law, although a tax treaty or qualifying European Union and Swiss relationship may reduce or remove the charge. Payments to non-resident companies for services provided in Estonia, including management and consultancy fees, are subject to 22% withholding tax under domestic law.
The standard value added tax rate is 24% from 1 July 2025 until 31 December 2028. Hotel accommodation services are taxed at 13%, while books, periodicals and listed pharmaceuticals are taxed at 9%. The value added tax registration threshold for taxable supplies of Estonian resident businesses or a fixed establishment of a non-resident business is €40,000 in a calendar year. Certain non-resident transactions require registration without a threshold.
Value added tax returns are generally monthly and are due, with payment, by the 20th day of the following month. The company’s activity, payment flows, customer location and presence in Estonia therefore affect registration, invoicing and recurring tax processes.
Hiring and managing employees in Estonia
Estonia’s Employment Contracts Act governs employment contracts, working conditions, wages and termination, alongside the Law of Obligations Act and other labour legislation. A written employment contract records the parties, start date, duties, workplace, pay, working time, holiday and termination terms. Recruitment and onboarding processes should capture these items before work begins.
Estonia normally operates an eight-hour day across a five-day week. The maximum working time is 48 hours per week including overtime, calculated over the applicable reference period, while absolute working time may not exceed an average of 52 hours in a seven-day period. Employees must receive at least 11 consecutive hours of daily rest and at least 48 hours of weekly rest under the standard arrangement.
Employees are entitled to at least 28 days of annual leave and Estonia has 12 public holidays. As of 1 April 2026, the minimum hourly wage is €5.67 and the minimum monthly wage for full-time work is €946. Overtime is generally paid at 1.5 times the regular wage or compensated with time off by agreement.
Employers pay social tax at 33%, with 20% allocated to public pension insurance and 13% to public health insurance. Employers also pay 0.8% unemployment insurance and withhold the employee contribution of 1.6%. In 2026, the minimum monthly basis for social tax is €886, resulting in a minimum employer social tax liability of €292.38.
Non-European Union citizens may register short-term employment or apply for a temporary residence permit for employment. Short-term employment for up to 365 days in a 455-day period must be registered before work starts. A European Union Blue Card may be issued to highly qualified foreign nationals. From 1 January 2026, employers hiring foreign workers face additional business activity and registration conditions, so immigration planning should begin before the proposed start date.
Regulatory compliance in Estonia
Domestic companies whose securities trade on a regulated market must use International Financial Reporting Standards as adopted by the European Union for consolidated financial statements. Credit institutions, insurance undertakings, financial holding companies, mixed financial holding companies and investment firms also use International Financial Reporting Standards. Most small and medium-sized enterprises may choose between these standards and Estonian Generally Accepted Accounting Principles.
Estonia has implemented the Common Reporting Standard and a Model I Foreign Account Tax Compliance Act agreement with the United States. Financial institutions within scope report specified account information to the Estonian tax authorities. These frameworks make customer classification, account data and recurring reporting central to the compliance model.
Estonia’s Base Erosion and Profit Shifting framework includes country-by-country reporting for multinational groups with consolidated revenue above €750 million, transfer pricing documentation and controlled foreign company rules. The Multilateral Instrument entered into force for Estonia on 1 May 2021 and modifies 58 Estonian tax treaties.
Anti-money laundering and ultimate beneficial owner requirements are governed mainly by the Money Laundering and Terrorist Financing Prevention Act. Obliged entities conduct Know Your Customer procedures covering client identity, ultimate beneficial owner verification and the purpose of the relationship. New entities submit ultimate beneficial owner data upon establishment and changes must be updated within 30 days. Customer and transaction data must generally be retained for at least five years.
FAQs
1. What is the most common company structure in Estonia?
Private limited companies and public limited companies are the forms most commonly used by foreign investors. The private limited company, or Osaühing (OÜ), offers limited shareholder liability and a low minimum capital requirement.
2. What is the minimum share capital for an Estonian OÜ?
The minimum share capital is €0.01 per shareholder.
3. What is the corporate income tax rate in Estonia?
The general corporate income tax rate is 24% from 1 January 2026. It applies to distributed profits rather than retained profits.
4. What is the standard VAT rate in Estonia?
The standard value added tax rate is 24% from 1 July 2025 until 31 December 2028. Reduced rates of 13% and 9% apply to specified supplies.
5. Can a foreign company establish a branch in Estonia?
Yes. The branch must register in the Estonian Commercial Register. It is not a separate legal person, so the foreign parent is liable for its obligations.
6. Do foreign workers need a permit in Estonia?
Non-European Union citizens may register for short-term employment or apply for a temporary residence permit for employment. The required route depends on the duration and nature of the work.
7. When must Estonian companies file annual financial statements?
Companies must file annual financial statements within six months after the end of the fiscal year.
Request our in-depth country profile to learn more about doing business in Estonia.
Request now Request now